Heston Model Simulation in Python
The Heston model is a mathematical framework used to describe the dynamics of financial derivatives, particularly options, in the context of stochastic volatility.
The model aims to address some of the limitations of the Black-Scholes model, which assumes that volatility is constant over time.
In the Heston model, volatility is not constant but follows a stochastic process, which means it can change over time due to market conditions.
This makes the model more flexible and realistic, as it can capture the observed volatility clustering phenomenon seen in financial markets.
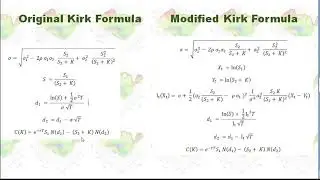
I compared Heston model and Black Scholes model.
Then I demonstrated how to run simulation for Heston model in Python.
You are welcome to provide your comments and subscribe to my YouTube channel.
The Python code is uploaded into https://github.com/AIMLModeling/Hesto...
Auf dieser Seite können Sie das Online-Video Heston Model Simulation in Python mit der Dauer stunde minuten sekunde in guter Qualität ansehen, das der Benutzer Statistics and Risk Modeling 13 August 2023 hochgeladen hat, den Link mit Freunden und Bekannten teilen, dieses Video wurde auf Youtube bereits 1,361 Mal angesehen und es wurde von 34 den Zuschauern gefallen. Viel Spaß beim Betrachtenden Zuschauern gefallen!