Simulating Ornstein-Uhlenbeck Process in Python
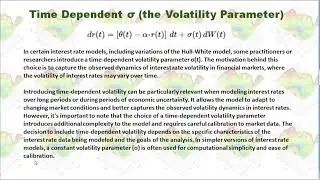
The Ornstein-Uhlenbeck (OU) process is a type of continuous-time stochastic process that is often used to model mean-reverting behavior.
It is a solution to a specific type of stochastic differential equation (SDE) and is widely used in various fields such as physics, finance, and biology.
The Ornstein-Uhlenbeck process is a key model for mean-reverting stochastic behavior, characterized by its tendency to revert to a long-term mean, along with random fluctuations.
I simulated the Ornstein-Uhlenbeck process, compared calculated parameters with theoretical parameters, analyzed first passage time.
You are welcome to provide your comments and subscribe to my YouTube channel.
The Python code is uploaded into https://github.com/AIMLModeling/Ornst...
In questa pagina del sito puoi guardare il video online Simulating Ornstein-Uhlenbeck Process in Python della durata di ore minuti seconda in buona qualità , che l'utente ha caricato Statistics and Risk Modeling 06 luglio 2024, condividi il link con amici e conoscenti, su youtube questo video è già stato visto 1,780 volte e gli è piaciuto 52 spettatori. Buona visione!