Hull White Term Structure Simulations in Python
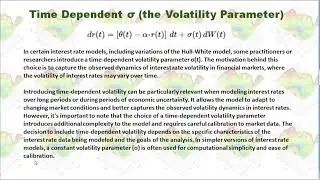
In financial mathematics, the Hull–White model is a model of future interest rates.
In its most generic formulation, it belongs to the class of no-arbitrage models that are able to fit today's term structure of interest rates.
I simulated the Hull White interest rate term structure model in Python and compared simulated average value and the analytical solution.
You are welcome to provide your comments and subscribe to my YouTube channel.
The Python code is uploaded into https://github.com/AIMLModeling/HullW...
On this page of the site you can watch the video online Hull White Term Structure Simulations in Python with a duration of hours minute second in good quality, which was uploaded by the user Statistics and Risk Modeling 04 February 2024, share the link with friends and acquaintances, this video has already been watched 2,119 times on youtube and it was liked by 38 viewers. Enjoy your viewing!