Hull White Term Structure Simulations in Python
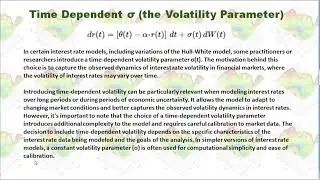
In financial mathematics, the Hull–White model is a model of future interest rates.
In its most generic formulation, it belongs to the class of no-arbitrage models that are able to fit today's term structure of interest rates.
I simulated the Hull White interest rate term structure model in Python and compared simulated average value and the analytical solution.
You are welcome to provide your comments and subscribe to my YouTube channel.
The Python code is uploaded into https://github.com/AIMLModeling/HullW...
Sur cette page du site, vous pouvez voir la vidéo en ligne Hull White Term Structure Simulations in Python durée heure minute seconde en bonne qualité , qui a été Téléchargé par l'utilisateur Statistics and Risk Modeling 04 février 2024, Partagez le lien avec vos amis et connaissances, sur youtube cette vidéo a déjà été regardée 2,119 fois et il a aimé 38 téléspectateurs. Bon visionnage!